My story
My Credit Went From the High 700s to the 300s. That's Why Fyyxit Exists.
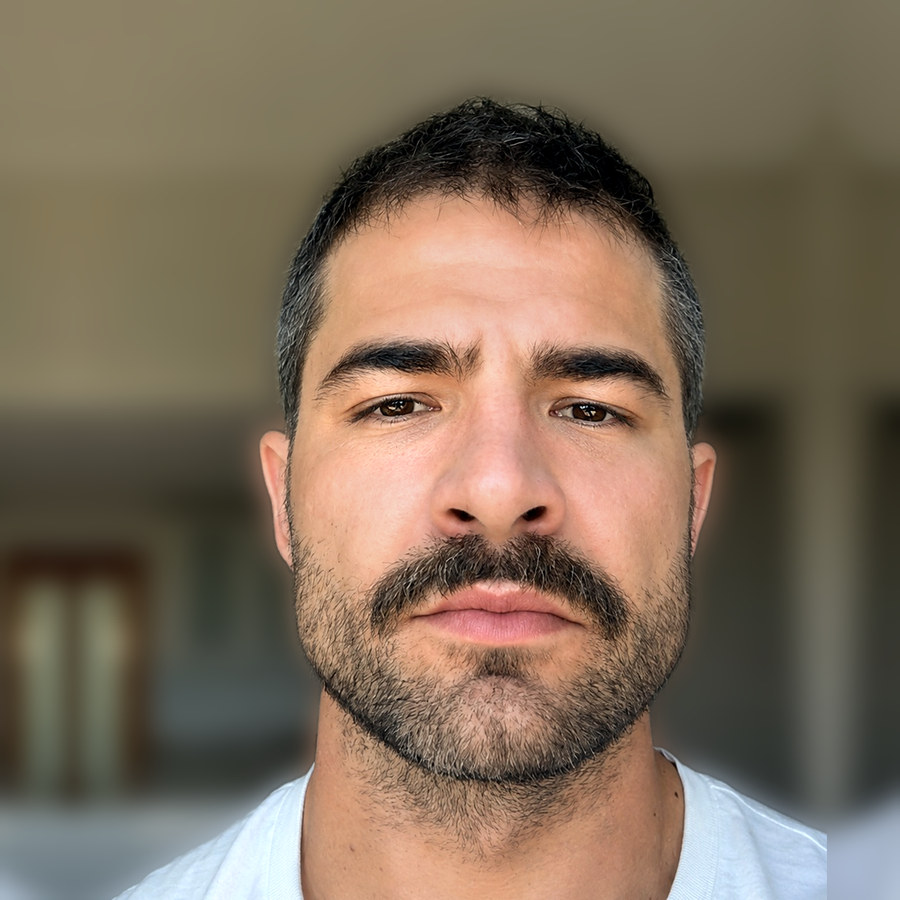
I've gone back and forth about how much of this to put out there. Some of it is embarrassing. Some of it still makes me angry. Some of it I'm still living through.
But if I'm asking you to trust Fyyxit with your credit, you deserve to know why I built it.
Nobody sits around thinking, "you know what would be a fun business? Credit repair software." I built Fyyxit because I watched my own credit collapse while I was trying to hold the rest of my life together, and then had to figure out how the hell to fix it.
It started with a flood
Before Fyyxit, I had a hair company. I'd spent almost a year and most of my money on the parts nobody sees: research, development, product, packaging, developers. The company had barely launched publicly.
Then my building flooded.
Product and belongings spread across my office and five storage units. Roughly $150,000 in claimed losses, not counting lost sales. I had renters insurance. I thought I'd done the responsible thing.
The insurance paid about $4,000.
There's a big difference between having insurance and understanding what it covers when everything goes wrong. I learned that the expensive way.
Then I hired a lawyer
The flood turned into a legal fight with my building. I hired an attorney so I could hand the problem to someone who knew what they were doing. That was the whole point.
I moved to Las Vegas to cut expenses while I kept paying for the lawsuit. Then COVID hit. Then, according to the allegations in the malpractice case I later filed, the attorney I was paying to fight for me failed to appear in court, and the case was lost.
That one still gets me. I didn't lose because I gave up. I lost while paying someone to fight for me.
I later learned I wasn't his only client with problems. I'm still in court over it today.
The number that follows you
While all of that was happening, my credit was getting destroyed.
I had always paid on time. High 700s. Then every dollar that should have gone to paying things off went to lawyers, moving, storage, and surviving.
My score dropped. And dropped. And dropped. All the way into the 300s.
Going from the high 700s to the 300s does something to you. Every time I fixed one problem, my credit created another. And somewhere in there, I also ended up in a fight with Capital One over nearly $50,000 in disputed rent charges. My other card companies sided with me. Capital One didn't, and by the time I understood what had gone wrong, the deadlines had already passed.
Companies have entire departments that know the rules and the deadlines. Regular people learn the rule after they've broken it, and the deadline after it's gone.
The $7,500 I won and then lost
Here's the part that really made Fyyxit happen.
I won a $7,500 grant toward an electric car through a California assistance program. Finally, a win.
Except I needed financing that met the program's requirements, and my credit was wrecked. I tried the required advisor. Different lenders. A cosigner. Extensions. I worked on my credit for months and got it up. Still not enough.
I lost the grant.
Think about that. An assistance program, designed for people who are struggling, that I couldn't use because I was struggling. You need a car to work. You need credit to get the car. Your credit is damaged because you've been struggling. So the loan costs more, and you sink further.
Around and around you go.
So I got obsessed
That's when I stopped being angry and started learning. Not the TikTok version. Not "add 100 points overnight."
I dug into the FCRA and the FDCPA, the actual laws that govern what credit bureaus, furnishers, and debt collectors can and can't do. I wanted to know exactly what was on my reports, who put it there, what was accurate, and what I had the right to challenge.
Then I built the tool I wished I'd had. Something that takes your reports and explains them in plain language, flags what might be inaccurate, and shows you what to do next, instead of leaving you staring at a report thinking "where do I even start?"
That's Fyyxit.
If this sounds like you
Maybe yours wasn't a flood. Maybe it was a divorce, a layoff, an illness, a business that failed, or helping someone you shouldn't have. Maybe you were 21 and made bad decisions. Maybe nobody ever taught you how credit worked. Or maybe you did everything right and life knocked you down anyway.
Your credit report doesn't know your story. It only knows data. And that data decides a lot about what happens next.
I'm not writing this from the other side. My credit still isn't perfect. Raising a score 400 points is a real battle, and I'm still in it. Still disputing. Still dealing with the legal fallout. Still building.
But I don't feel powerless anymore. I know how to read what's being reported about me, ask questions, and keep records. And I know that one person against a giant corporation doesn't mean the corporation gets to ignore the rules.
That's what I want Fyyxit to give you. No false promises. No "we'll delete everything." No magic loophole. Just a fighting chance: the ability to look at your own information, understand it, say "wait, this doesn't look right," and know what to do next.
Where I am now
There have been stretches in the last few years when paying for basic things wasn't easy. I've wondered where I'd live. I've wondered whether everything I'd built was just gone. Yes, I've had moments I wanted to quit.
But I'm still here.
Maybe being a survivor isn't some incredible comeback where everything suddenly turns perfect. Maybe it's less glamorous than that. Maybe it's waking up the next morning and trying again. Then doing it again. And again.
Theodore Roosevelt wrote about the person who steps into the arena knowing he might fail, but who fails "while daring greatly." The alternative, he said, is to be one of the "cold and timid souls who neither know victory nor defeat."
I'd rather be in the arena.
I'm not finished. Fyyxit isn't finished. And maybe you're not finished either.
Start where you are
If you're looking at a 400 right now, start there. If you're at 650 trying to hit 700, start there. If there's one account you know is wrong, start with that one.
You don't have to fix your whole financial life today. Just stop telling yourself there's nothing you can do.
I'm saying that as someone who went from the high 700s to the 300s and is still fighting his way back.
So let's do it together. One report. One account. One dispute. One point at a time.
And when something isn't right?
Let's Fyyxit.
— Andrew, Founder of Fyyxit